The seller: two related companies, an open quarter & a bank conversation coming
The client sells wheels and tires online, across multiple marketplaces. Behind the storefront sit two related companies.
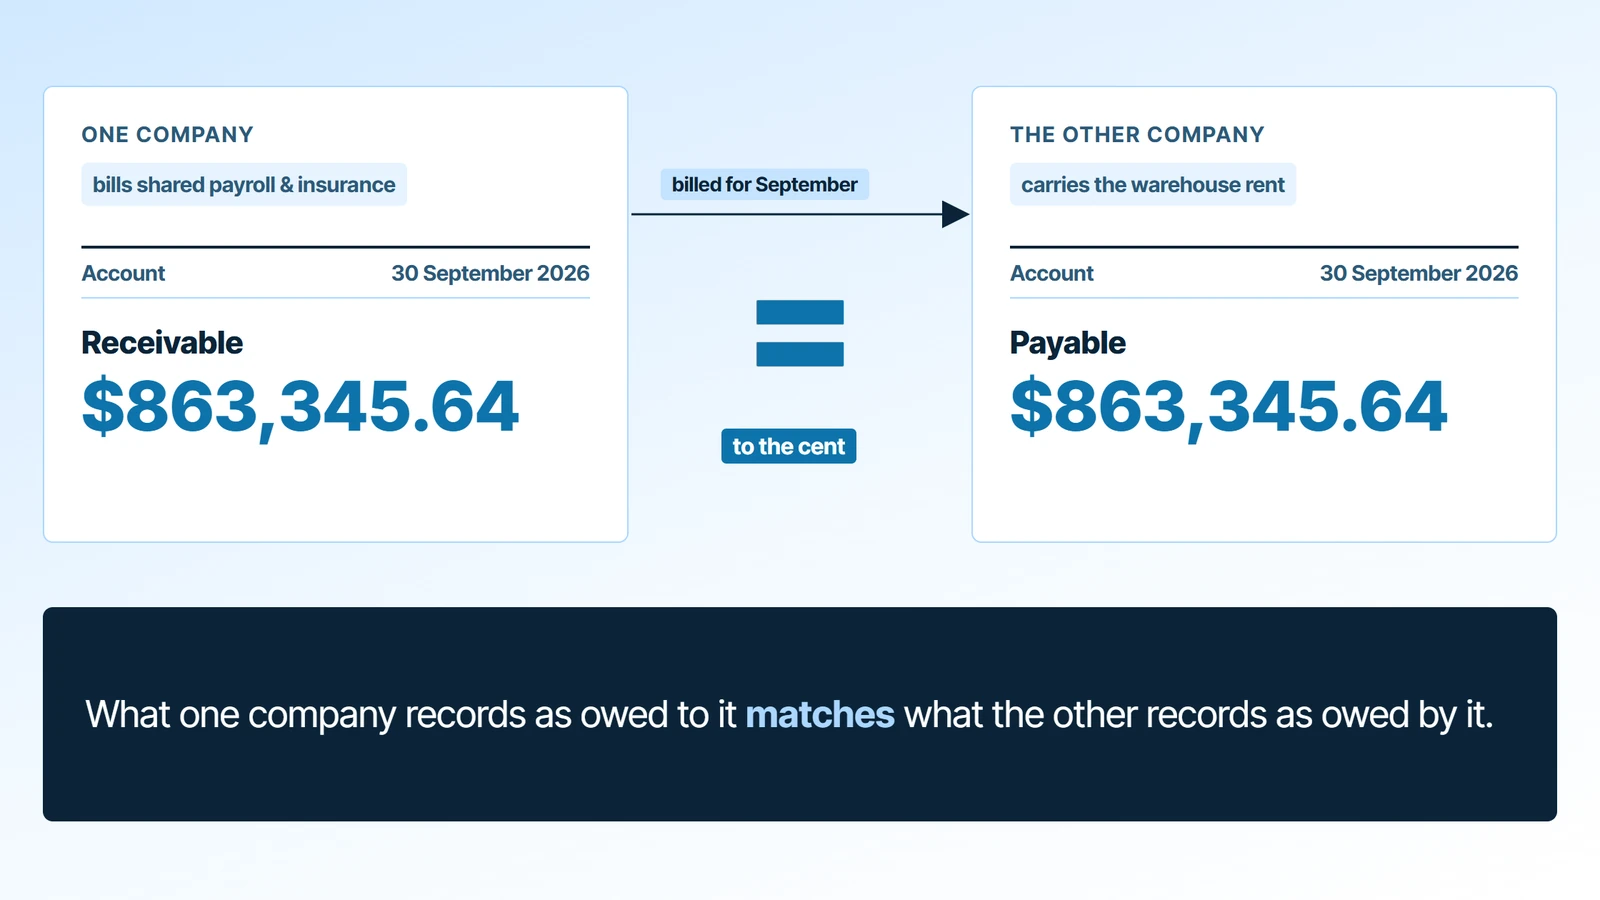
One company bills the other for shared costs like payroll and insurance. The second company carries the warehouse rent.
The business is run by a hands-on general manager. He reads his own financials every month & knows his numbers cold.
When he decided to take those numbers to the bank, he came to us with one request. A clear list of what was left to do before the figures were strong enough for a lender. He did not want a sales pitch.
The thing is that a bank does not read financials the way an owner does. An owner reads for the story. A lender reads for the numbers that do not agree. With two companies, the first place that happens is between them.
And the books were not there yet. The quarter was still open. September intercompany allocations had not been posted. Two credit card statements and one supplier bill were still outstanding.
What one company recorded as owed to it also had to match, to the cent, what the other recorded as owed by it. On top of that, the bank wanted more than history. It wanted a sales forecast by platform and the owner’s expansion plan.
Loose ends do not stay small when a bank is reading. One figure that does not agree and the lender starts checking everything else. For a growing online seller that can mean a delayed decision, a smaller facility or tougher terms, right when capital is needed to expand.
With GATP: Q3 closed for both companies & $863,345.64 matched to the cent
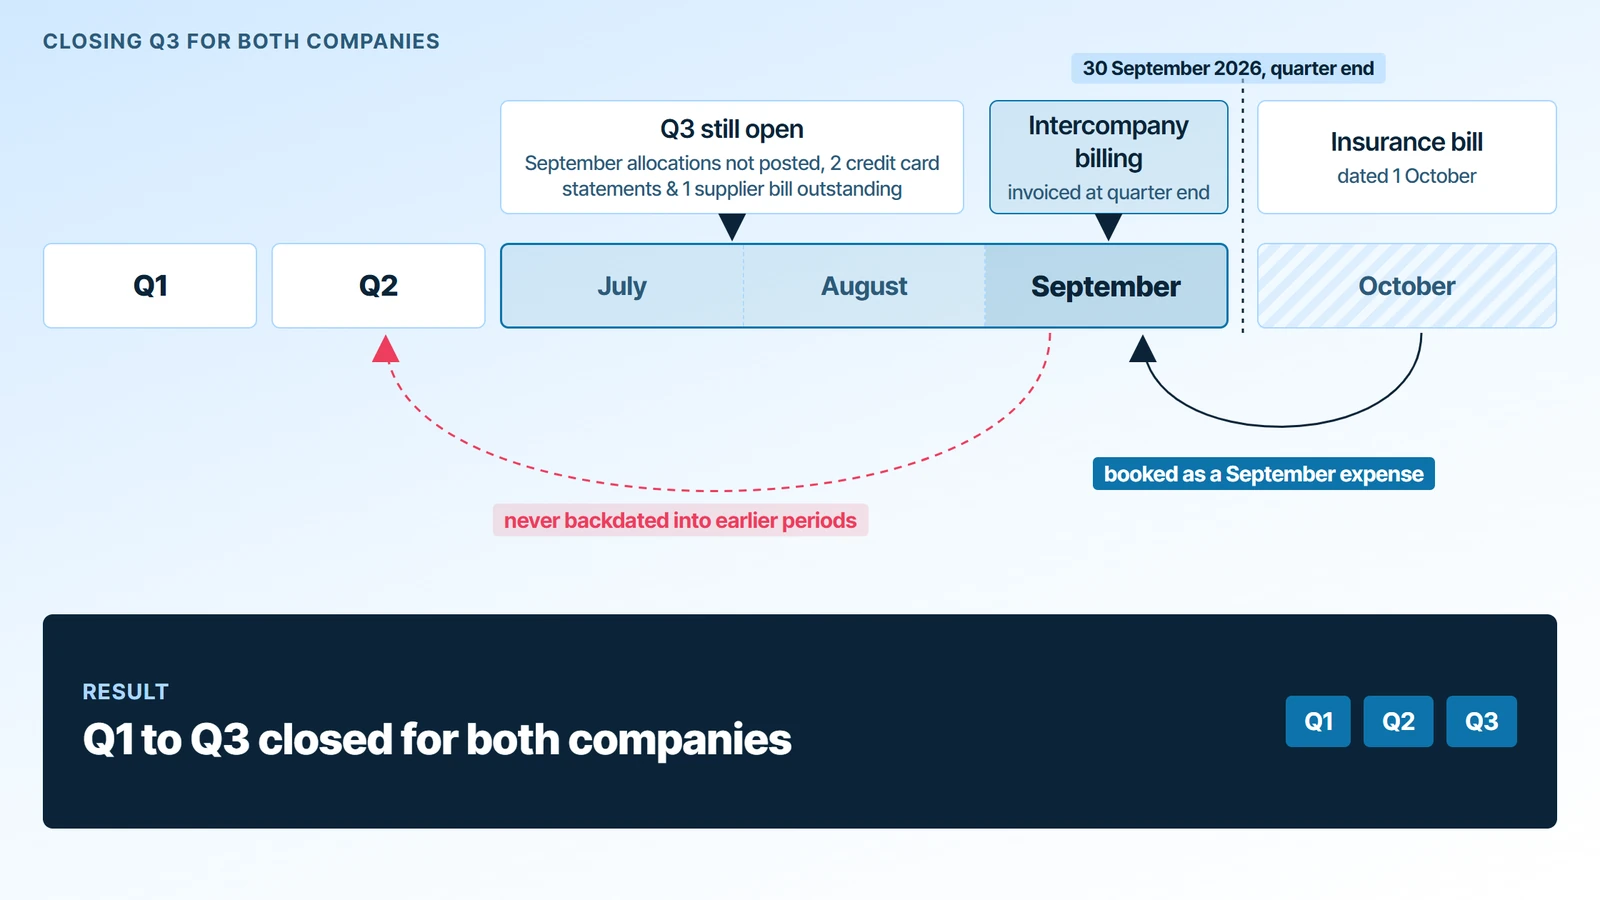
We worked it in the order a bank reads it. Close the quarter, make the two companies agree, then build the consolidated package.
First the quarter. We requested the outstanding credit card statements and received them.
We also found a September insurance bill dated 1 October. We confirmed it with the owner and booked it as a September expense. The cost landed in the quarter it belonged to.
Then the intercompany billing. Shared payroll and insurance were billed between the two companies for September and invoiced at quarter end. Nothing was backdated into earlier periods.
At 30 September 2026, the receivable in one company and the payable in the other matched exactly at $863,345.64. To the cent.
Shared costs booked the way a lender expects, then one consolidated package
Accurate books are one thing. Bank-ready books are books that survive scrutiny. Every shared cost on a defensible basis, every intercompany balance tied out, every forecast explainable.
Payroll was split across quarters by the days the team actually worked.
Insurance was accrued across the full year. A single annual premium does not distort one quarter and flatter another.
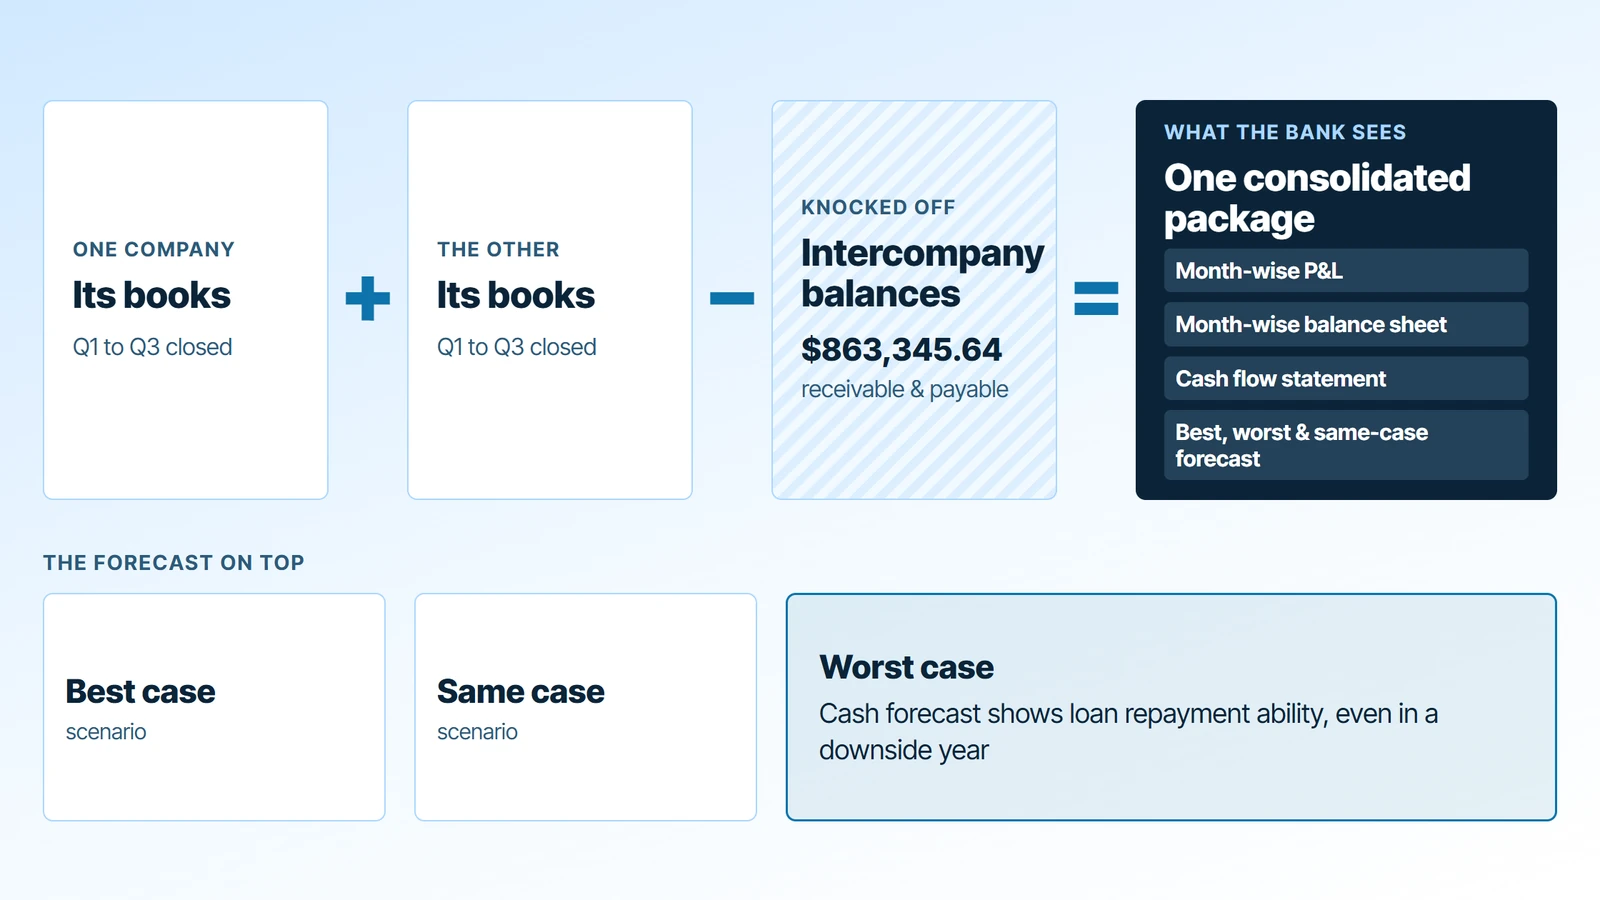
Then the package itself. A month-wise profit and loss statement, a month-wise balance sheet and a cash flow statement showing cash generated from operations.
Everything was consolidated, with intercompany balances knocked off. Two separate ledgers stapled together tell the bank two stories. Consolidated financial statements show one business & one number.
On top of the history, we built a forecast with best, worst and same-case scenarios. It includes a cash forecast that shows the business can repay the loan even in a downside year.
Q1 to Q3 closed, with nothing in the package that invites a lender to dig
The general manager asked for a clear list and got a complete set of statements he can hand over with confidence. The results are pretty clear:
- Q1 to Q3 are complete for both companies, backed by closed financial statements for each entity.
- The intercompany balance matches to the cent at $863,345.64.
- One set of consolidated financial statements, so the bank sees a single business.
- A best, worst and same-case forecast, with a cash forecast that shows loan repayment ability in a downside year.
- A clear, ordered list of what a bank will examine and in what sequence.
He no longer has a to-do list he had to build on his own. He walks into the bank with books that tie out and a forecast that answers the lender’s real question before it is asked. Can this business repay in a bad year?
By closing the quarter and matching what each company owes the other to the cent, GATP helped the seller take one consolidated number to the bank.
LET’S TALK
If you own more than one company and a bank conversation is coming, start with what each company owes the other. That is the first place a lender looks too.
Closing the quarter, reconciling intercompany balances to the cent and consolidating the package is everyday outsourced accounting work GATP does for 7-figure e-commerce sellers.
Contact GATP to talk through your numbers before the bank does.