
Monthly bookkeeping means your books are recorded, reconciled and closed every month, and a median in-house bookkeeper costs $6,150 a month to do it. Monthly bookkeeping services sell that same close for a fixed fee, and this guide covers what they include, the 7-step month-end close and what they should cost in 2026.
If your company does $1 million to $10 million a year, you rarely need a bookkeeper 40 hours a week. You need the close done right, on a set date, by someone whose work gets reviewed. That is the case for outsourced bookkeeping services priced by the hours your books actually take.
What Is Monthly Bookkeeping?
Monthly bookkeeping is a recurring service that records, reconciles and reports your business’s transactions every month, instead of once a year at tax time. Each month ends with books that match the bank and a set of statements you can act on.
A monthly cycle has 5 parts:
- Record and categorize: every sale, bill and bank transaction coded to the right account.
- Reconcile: each bank and credit card account matched to its statement.
- Review open items: unpaid customer invoices and unpaid bills checked.
- Close the month: adjusting entries posted and the period locked.
- Report: financial statements delivered to you.
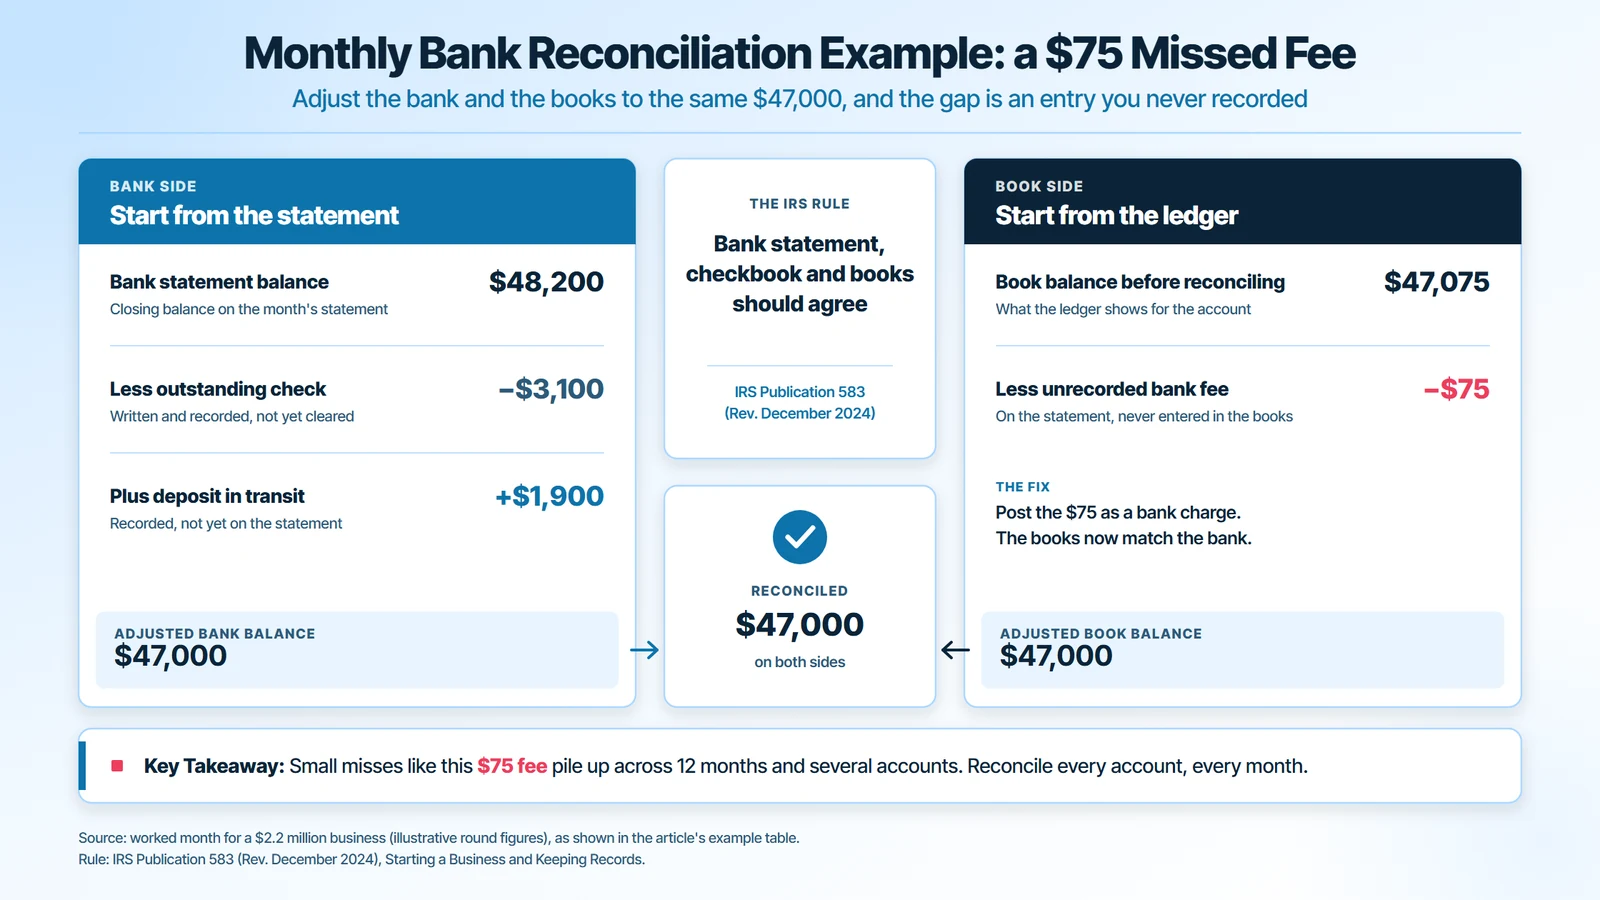
The rule behind the cycle comes from the IRS. IRS Publication 583 says that when your bank statement arrives, the statement, your checkbook and your books should agree. A monthly close makes that true 12 times a year.
Example month for a $2.2 million business
Item | Amount |
Revenue for the month | $185,000 |
Expenses for the month | $162,000 |
Net profit | $23,000 |
Bank statement balance | $48,200 |
Less outstanding check | $3,100 |
Plus deposit in transit | $1,900 |
Adjusted bank balance | $47,000 |
Book balance before reconciliation | $47,075 |
Difference: unrecorded bank fee | $75 |
The reconciliation found a $75 bank fee the books never recorded. Small misses like that pile up across 12 months and several accounts, which is the point of doing the work monthly.
Monthly bookkeeping keeps the current month clean. Catch-up bookkeeping fixes months that were never done, and it is usually priced as a one-off project. If you are behind, catch-up bookkeeping services bring the books current first, then the monthly cycle keeps them there.
What Does Monthly Bookkeeping Include?
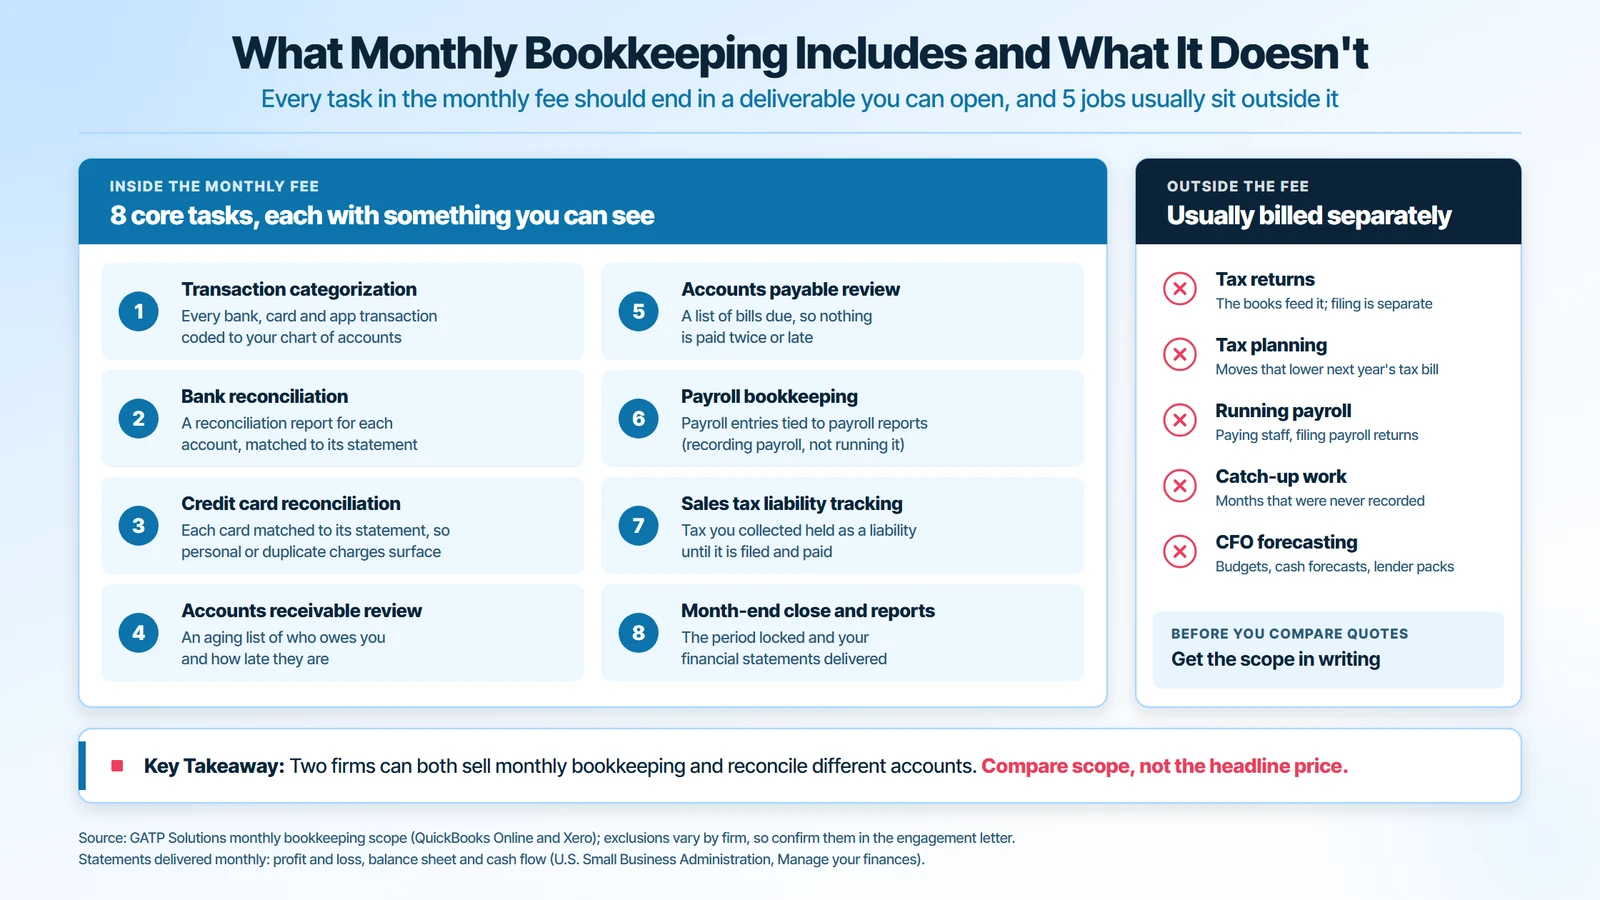
Monthly bookkeeping includes categorized transactions, reconciled bank and credit card accounts, updated receivables and payables, a month-end close and a set of financial statements. The core set is 8 tasks, and each one should end in something you can see:
- Transaction categorization: every bank, card and payment-app transaction coded to your chart of accounts in QuickBooks Online or Xero, the two ledgers GATP works in.
- Bank reconciliation: each bank account matched to its statement, with a reconciliation report you can open.
- Credit card reconciliation: each card matched to its statement, so personal or duplicate charges surface.
- Accounts receivable review: an aging list of who owes you and how late they are.
- Accounts payable review: a list of bills due, so nothing is paid twice or late.
- Payroll bookkeeping: payroll entries recorded and tied to the payroll reports. Recording payroll is not the same as running it.
- Sales tax liability tracking: tax you collected held as a liability until it is filed and paid.
- Month-end close and reports: the period locked and your statements delivered.
Payroll and contractor payments also carry 2026 IRS rules, such as the deposit dates in Step 4 and the $2,000 Form 1099-NEC threshold in Step 6. Put the exact scope in your engagement letter. Two firms can both sell “monthly bookkeeping” and reconcile a different number of accounts.
Financial Statements: Profit and Loss, Balance Sheet and Cash Flow
Every month you should receive 3 financial statements: a profit and loss statement, a balance sheet and a cash flow statement. Most firms add aging reports for receivables and payables. The U.S. Small Business Administration calls the balance sheet the foundation of your statements and a snapshot of your business’s finances.
Statement | What it answers | What to check each month |
Profit and loss | Did we make money this month? | Gross margin and any expense line that jumped |
Balance sheet | What do we own and owe on the last day? | Cash matches the reconciliation; loan balances match lender statements |
Cash flow statement | Where did the cash go? | Cash from operations against profit |
Receivable and payable aging | Who owes us, and whom do we owe? | Invoices and bills past due |
Read them together. A profitable month on the profit and loss can still drain cash on the cash flow statement.
What Monthly Bookkeeping Does Not Include
Tax return preparation, tax planning, running payroll, catch-up work and CFO forecasting usually sit outside a monthly bookkeeping fee. Check for these 5 items before you compare quotes:
- Tax returns: the books feed the return, but filing it is a separate job.
- Tax planning: moves that lower next year’s tax bill.
- Running payroll: paying staff and filing payroll returns.
- Catch-up work: months that were never recorded.
- CFO forecasting: budgets, cash forecasts and lender packages.
GATP is a CPA firm, and its Premium plan adds federal and state tax work to the monthly books.
Monthly Bookkeeping Checklist: The Month-End Close in 7 Steps
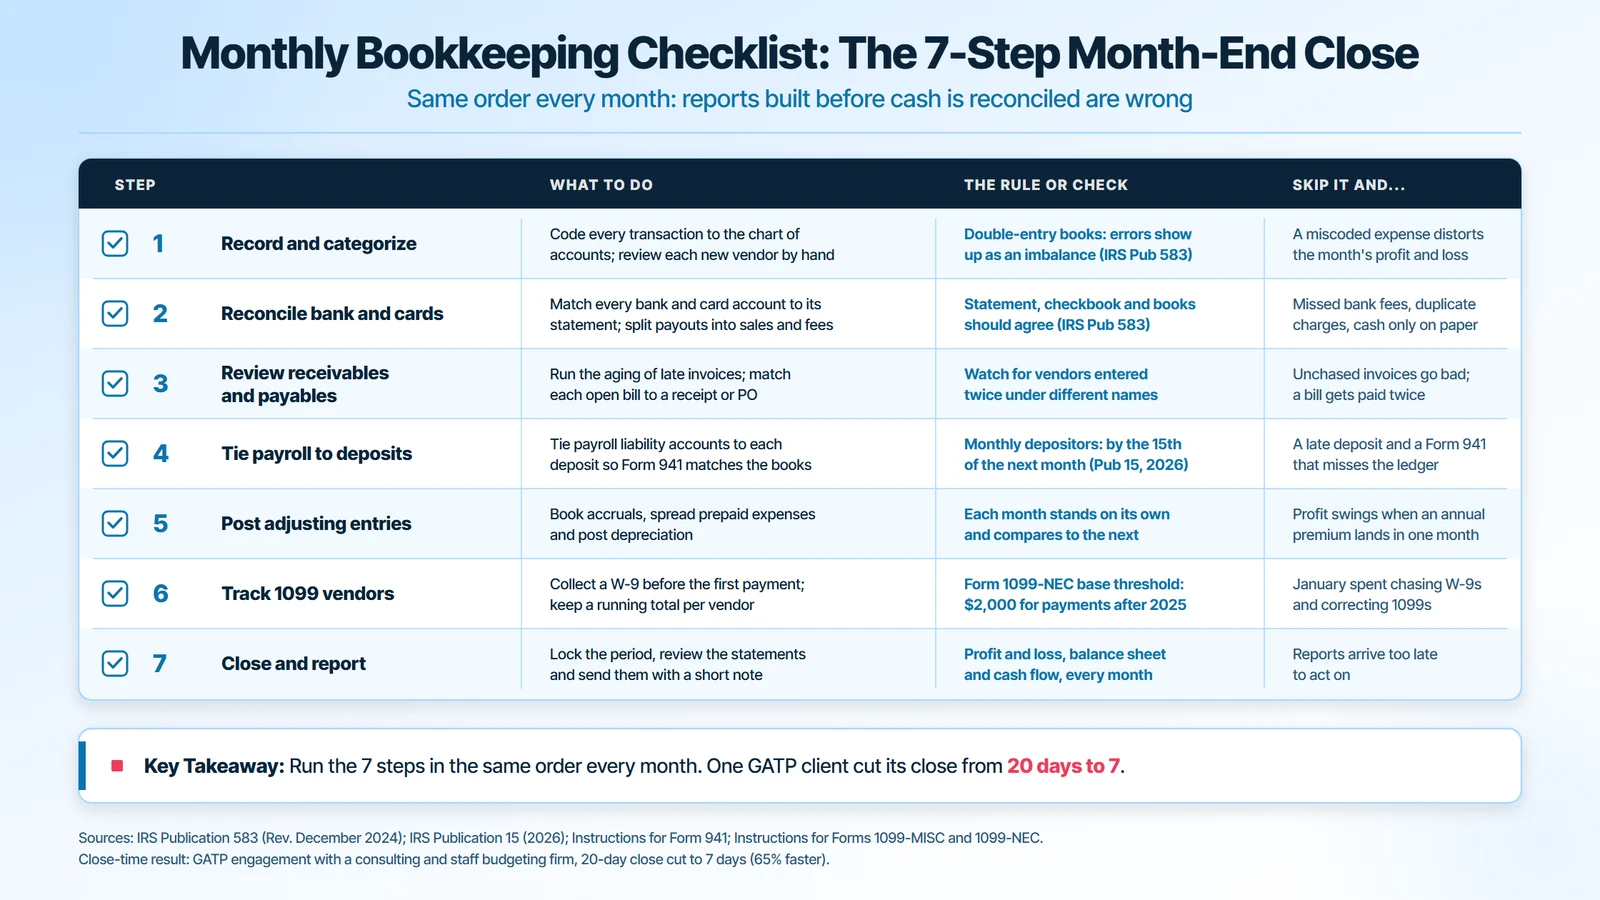
The monthly bookkeeping checklist is the month-end close: 7 steps run in the same order every month. Order matters, because reports built before cash is reconciled are wrong. If you still keep the books yourself, the same steps apply to small business bookkeeping done in-house.
Step 1: Record and Categorize Transactions Against the Chart of Accounts
Step 1 records every transaction from the month and codes it to an account in your chart of accounts. Bank feeds in QuickBooks Online pull the transactions in. A person still has to check each category.
IRS Publication 583 describes two systems, single-entry and double-entry. A business your size wants double-entry, because each transaction hits two accounts and errors show up as an imbalance. Set vendor rules for repeat payees, and review every new vendor by hand.
Skip it and a miscoded expense, such as equipment booked as supplies, distorts your profit and loss for the month.
Step 2: Run the Bank Reconciliation and Credit Card Reconciliation
Step 2 matches every bank and credit card account to its statement balance. Start from the statement, list outstanding checks and deposits in transit, and compare the adjusted balance to the books. The $75 example above is that test in action.
Card processors and payment apps need their own pass, because a payout lands net of fees. A payment reconciliation splits each payout into sales, fees and refunds before you match it to the deposit. Any difference left over is a missing or wrong entry.
Skip it and you miss bank fees, duplicate charges and cash that exists only in the books.
Step 3: Review Accounts Receivable and Accounts Payable
Step 3 reviews both sides of credit. Run the accounts receivable aging and list every invoice past its due date, by customer. Then run accounts payable and match each open bill to a receipt or purchase order.
Watch for vendors entered twice under slightly different names. Duplicate vendors are a common cause of double payments. Agree up front on who chases late customers and who approves bills, because a bookkeeper who only records will not collect.
Skip it and an invoice nobody chased becomes a bad debt, while a bill gets paid twice.
Step 4: Tie Payroll to the IRS Deposit Schedule and Form 941
Step 4 checks that payroll in the books matches what you paid and deposited. Under IRS Publication 15 (2026), you are a monthly schedule depositor if your employment taxes in the lookback period were $50,000 or less. Monthly depositors deposit each month’s taxes by the 15th day of the following month. Larger payrolls deposit semiweekly.
Form 941 reports those wages and taxes each quarter. The Instructions for Form 941 set the due dates at April 30, July 31, October 31 and January 31. Tie the payroll liability accounts to the deposits every month, so the quarter’s Form 941 matches the books.
Skip it and you risk a late deposit and a Form 941 that does not match your ledger.
Step 5: Post Accruals, Prepaid Expenses and Depreciation
Step 5 posts the adjusting entries that make each month stand on its own. An accrual records an expense you incurred but were not yet billed for, such as wages earned in the last days of the month.
A prepaid expense spreads one payment, such as an annual insurance premium, across the months it covers. Depreciation spreads the cost of equipment over its useful life. These entries matter on accrual books, and they make one month comparable to the next.
Skip it and your profit and loss swings because a quarterly bill or an annual premium landed in a single month.
Step 6: Track 1099 Vendors Against the 2026 $2,000 Threshold
Step 6 tracks payments to contractors and other vendors who may need a Form 1099-NEC or 1099-MISC. The Instructions for Forms 1099-MISC and 1099-NEC raise the base reporting threshold to $2,000 for payments made after December 31, 2025.
The old threshold was $600, and the new one may be adjusted for inflation from 2027. One payment type stays at $600: gross proceeds paid to an attorney, reported in box 10 of Form 1099-MISC.
Flag each new vendor as reportable or not on the first payment. Collect a Form W-9 before you pay, and keep a running total per vendor in your accounting software.
Skip it and you spend January chasing W-9 forms and correcting 1099s.
Step 7: Close the Month and Deliver the Financial Statements
Step 7 locks the period and delivers the reports. Closing means setting a closing date in the software so no one can post to the month. Then someone reviews the statements for anything unusual and sends them to you with a short note.
Speed matters more than most owners expect. A consulting and staff budgeting firm cut its close from 20 days to 7 days with GATP, a 65% faster month-end close, and saw 70% fewer 1099 corrections. The gain came from automated categorization plus a senior reviewer on the output. A 20-day close means you read numbers that are already 20 days old.
Skip it and your reports arrive too late to act on.
How Much Should Monthly Bookkeeping Cost in 2026?
Monthly bookkeeping should cost about what the bookkeeper hours behind it cost: $35.48 an hour for a median bookkeeper once benefits are added. GATP’s fixed-fee plans start at less than $250 a month.
The hourly figure comes from 2 federal sources. The Bureau of Labor Statistics wage data put the median bookkeeper wage at $24.36 an hour in May 2025. BLS Employer Costs for Employee Compensation show office staff cost $36.73 an hour in total compensation against $25.22 in wages, in June 2026. Scaling the wage by that ratio gives $35.48.
Monthly bookkeeping services cost more or less depending on 5 drivers:
- Transactions per month: the biggest driver of hours.
- Bank and card accounts: each one is its own reconciliation.
- Payroll: entries, liability accounts and deposit checks.
- Sales tax, receivables and payables: collections and bill payment add hours.
- Cash or accrual books: accruals and prepaid schedules add a monthly layer.
What a monthly bookkeeping fee buys at the 2026 median rate
Bookkeeper hours a month | Cost at $35.48 an hour | Typical fit |
10 hours | $355 | A single entity with one bank and one card account |
20 hours | $710 | Adds payroll and bill payment |
40 hours | $1,419 | Several accounts, receivable follow-up and accrual entries |
173 hours | $6,150 | A full-time in-house bookkeeper |
Use the table to test monthly bookkeeping fees. A quote far below the hours your books need means a narrower scope. If you are weighing an in-house bookkeeper against a firm, the answer to how much does a bookkeeper cost starts with that $6,150 monthly figure.
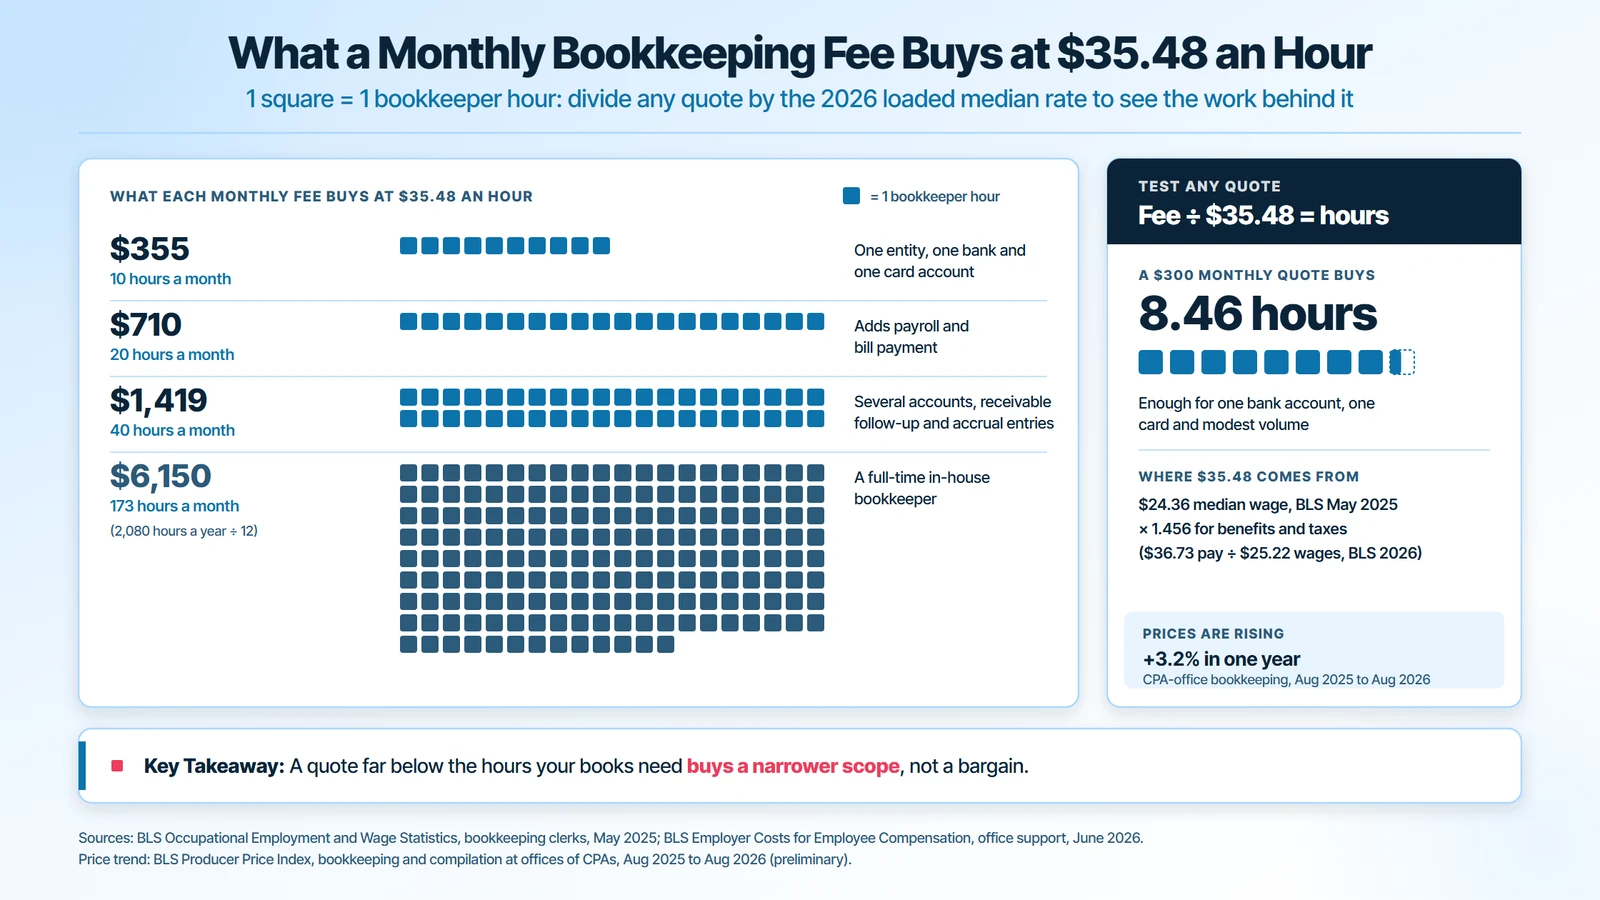
Prices are also rising. Producer prices for bookkeeping and compilation work at CPA offices rose 3.2 percent from August 2025 to August 2026, on preliminary BLS data.
Fixed Monthly Fee vs Hourly Billing
A fixed monthly fee caps your bill and suits a recurring close. Hourly billing suits one-off catch-up or cleanup work. Compare the 2 models on these terms:
Model | How the bill is set | Best for | Watch for |
Fixed monthly fee | An agreed scope at one price each month | The ongoing monthly close | Scope limits, contract term and notice period |
Hourly billing | Hours worked times a rate | Catch-up and cleanup projects | No cap on the bill |
Read the contract term before you sign. GATP, for example, runs annual subscription contracts with a 30-day notice period to cancel or change them.
Bookkeeping Packages: What Each Monthly Tier Should Include
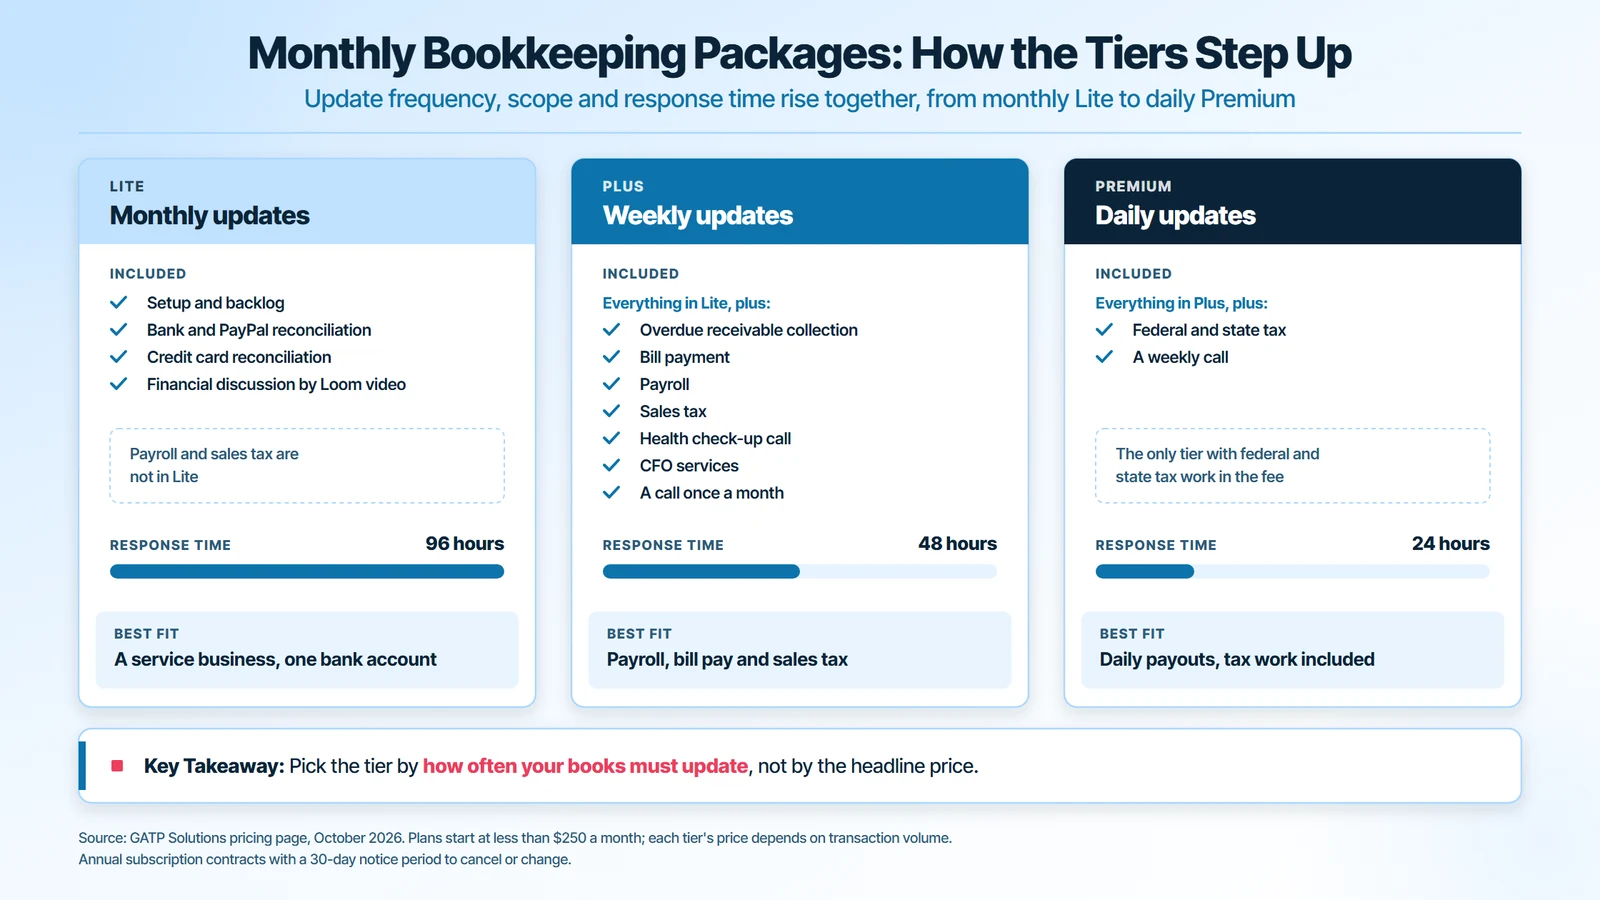
Bookkeeping packages differ in 3 ways: how often the books are updated, which accounts are reconciled, and whether payroll, sales tax and tax returns are in scope. GATP’s monthly bookkeeping packages show how the tiers usually step up:
Package | Update frequency | Included | Added at this tier |
Lite | Monthly | Setup, backlog, bank, PayPal and credit card reconciliation | Financial discussion by Loom video; 96-hour response |
Plus | Weekly | Everything in Lite | Overdue receivable collection, bill payment, payroll, sales tax, health check-up call, CFO services; a call once a month; 48-hour response |
Premium | Daily | Everything in Plus | Federal and state tax; a weekly call; 24-hour response |
GATP’s plans start at less than $250 a month. The price of each tier depends on your volume, so the pricing page publishes only the starting point.
Pick the tier by the update frequency you need. A service business with one bank account can run on monthly updates. A business with daily payouts, payroll and sales tax filings usually needs weekly or daily work.
Monthly Bookkeeping vs Monthly Accounting Services
Monthly bookkeeping keeps the records current and reconciled. Monthly accounting services add review, adjusting entries, tax planning and advice on top. The 2 differ in 4 ways:
Question | Monthly bookkeeping | Monthly accounting services |
Who does it | A bookkeeper | An accountant or CPA, often with a bookkeeper |
What you get | Reconciled books and statements | Reviewed statements, analysis and tax planning |
How often you talk | Email or a recorded summary | A scheduled call |
What it prepares you for | An accurate tax return | Decisions on pricing, hiring and cash |
Many firms blend the two. At GATP, tax work and CFO time sit in the higher tiers.
How to Choose a Monthly Bookkeeper
Choose a monthly bookkeeper on scope, close date and reviewer, not on the headline price. Ask these 6 questions:
- Which accounts do you reconcile every month? Prevents a quote that leaves out a card or a payment app.
- What day of the following month do the books close? Prevents reports that arrive too late to use.
- Who reviews the bookkeeper’s work? Prevents errors that nobody catches until tax season.
- Are payroll and 1099 tracking in scope? Prevents a January scramble for W-9 forms.
- What is the contract term and notice period? Prevents surprise lock-ins. An annual contract with 30 days’ notice is a common term.
- Which software is used, and who owns it? Prevents losing your history when you switch. GATP works in QuickBooks Online and Xero, and you keep ownership.
What Changed for Monthly Bookkeeping in 2026
The base Form 1099-NEC and 1099-MISC threshold rose from $600 to $2,000 for payments made after December 31, 2025. Four changes reach the monthly checklist in 2026:
- 1099-NEC and 1099-MISC at $2,000: fewer vendors need a form, and the threshold may be adjusted for inflation from 2027.
- Form 1099-K back to $20,000: payment apps and online marketplaces report only payments over $20,000 in more than 200 transactions. Your monthly books, not a 1099-K, must carry every processor payout.
- Cash-method test at $32,000,000: for tax years beginning in 2026, the Section 448(c) gross receipts test is $32,000,000, averaged over the 3 prior years, under Rev. Proc. 2025-32. A business with $1 million to $10 million in receipts sits well under it, but accrual books still give a truer monthly picture.
- Prices up 3.2 percent: bookkeeping and compilation prices at CPA offices rose 3.2 percent from August 2025 to August 2026.
Conclusion: Monthly Bookkeeping Comes Down to the Close
Monthly bookkeeping is the record, reconcile and close cycle run every month, ending in statements you can act on. The price follows the hours your transactions, accounts and payroll need, at $35.48 an hour for a median bookkeeper.
Want to know if your monthly close is on time and complete? GATP’s CPAs will review last month’s bank reconciliation and the day your books closed, in a 30-minute call. You get a list of the gaps and a monthly bookkeeping package matched to your transaction volume, drawn from our pricing plans.
Frequently Asked Questions
Can I Do My Bookkeeping Myself?
Yes, you can do your own bookkeeping, and the IRS accepts either a single-entry or a double-entry system. The real question is cost. Each hour you spend has a market value of $35.48, the loaded median bookkeeper rate, If your hour earns more than $35.48 elsewhere in the business, handing off the close pays for itself.
Should Small Business Bookkeeping Really Cost $300 a Month?
$300 a month is fair only for simple books. At the 2026 loaded median rate of $35.48 an hour, $300 buys 8.46 hours of bookkeeper time. That covers one bank account, one card and modest volume. Add payroll, more accounts or accrual entries and the hours, and the fee, go up.
Can ChatGPT Do My Bookkeeping?
No, ChatGPT cannot do your bookkeeping on its own, because it does not hold your ledger or reconcile your bank. AI tools can speed up categorization. In one GATP engagement, automated categorization helped cut a close from 20 days to 7 days, and it worked because a senior reviewer checked the output.
How Long Should I Keep Monthly Bookkeeping Records?
Keep monthly bookkeeping records for at least 3 years, the general IRS period of limitations. Keep employment tax records for at least 4 years after the tax is due or paid. File bank statements, reconciliation reports and receipts with each month’s close, so you can support any figure on a return.
Should Monthly Bookkeeping Use Cash or Accrual Accounting?
Accrual accounting gives the truer monthly picture if you carry receivables, payables or inventory, because it matches revenue and costs to the right month. Cash books are simpler. For tax years beginning in 2026, businesses with average gross receipts of $32,000,000 or less over 3 prior years generally pass the cash-method test.
Does Monthly Bookkeeping Include Payroll?
Monthly bookkeeping includes recording payroll, but running payroll is usually a separate service. At GATP, payroll is in the Plus and Premium plans, not in Lite. Either way, the books should tie each month’s payroll taxes to the deposit, due by the 15th day of the following month for monthly depositors.
Does Monthly Bookkeeping Include Tax Preparation?
No, tax preparation usually sits outside a monthly bookkeeping fee. The monthly books feed the return, but preparing and filing it is a separate engagement. At GATP, federal and state tax work is included only in the Premium plan. Clean monthly books shorten tax season, because the year-end close becomes the 12th monthly close.
Do S Corps Need Monthly Bookkeeping?
No IRS rule requires an S corporation to close its books monthly, but payroll makes it the practical choice. The IRS expects records that support every figure on the return. An S corp usually pays its working owner a wage, so payroll taxes follow the deposit schedule, by the 15th of the following month for monthly depositors.

